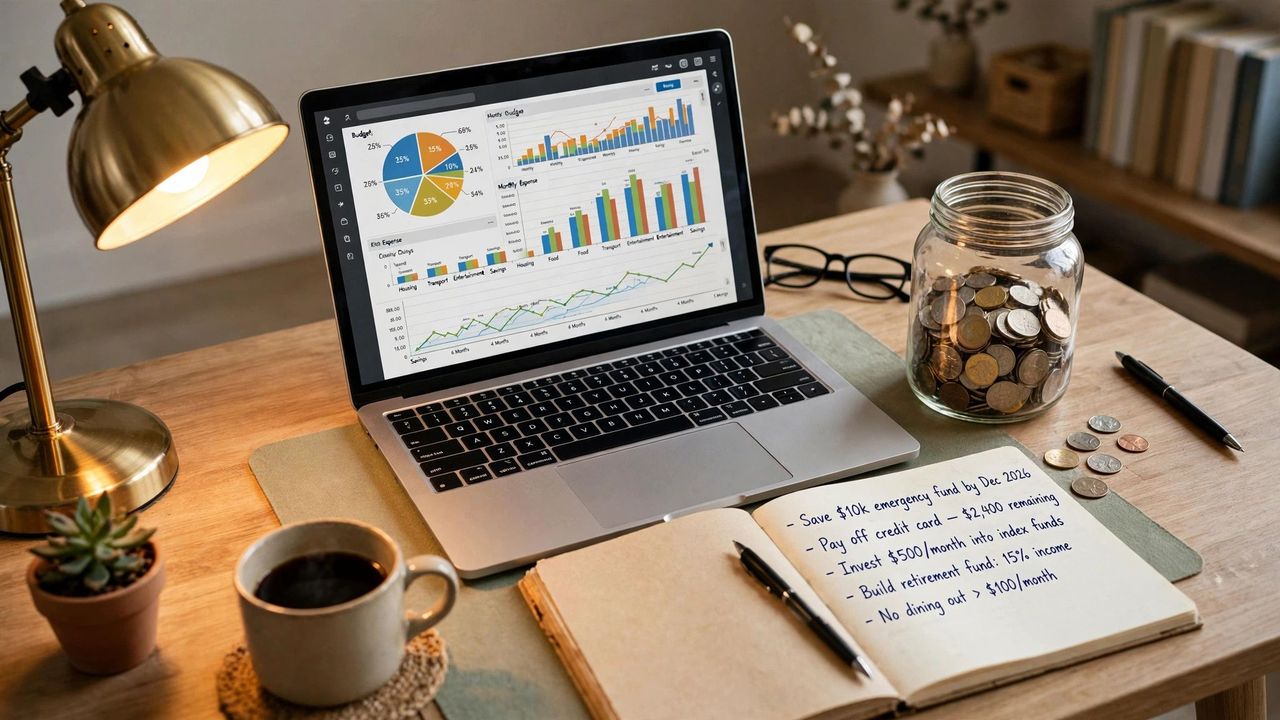
"Save more money" fails as a resolution for the same reason "get fit" does: it is a wish, not a plan. Money goals work when they are specific, automated, and sized to your actual income. Whether 2027 is the year you kill a credit card balance, build your first emergency fund, or finally start investing, here is the realistic playbook.
Start with a Money Snapshot
You cannot plan what you cannot see. In the first week of January, do two things. First, list every debt with its balance and interest rate, and every account with its balance: checking, savings, retirement. That is your net worth, and knowing it is step one. Second, track every dollar you spend for one month. Not to judge it, to see it. Most people discover 100 to 300 dollars a month leaking to subscriptions, food delivery, and impulse buys they do not even enjoy. You do not need a perfect budget yet; you need honest data. A free budgeting app or a simple spreadsheet both work.
The Emergency Fund: Your First Target
Before investing, before extra debt payments, build a starter emergency fund of 1,000 dollars (or one month of essential expenses, whichever is smaller). This is the buffer that stops a car repair from becoming credit card debt. Keep it in a separate high-yield savings account, not your checking, so spending it takes deliberate effort. Once the starter fund exists, grow it toward three to six months of essential expenses. That larger fund is what lets you survive a job loss without panic. Automate a transfer on every payday, even 25 dollars, and the fund builds while you sleep.
Kill High-Interest Debt
Debt with interest above 8 percent, usually credit cards, is a financial emergency wearing a monthly minimum payment disguise. Two proven payoff methods: the avalanche (pay minimums on everything, throw extra cash at the highest-rate balance first) saves the most money mathematically. The snowball (attack the smallest balance first for quick wins) works better psychologically for most people. Pick the one you will actually stick with. A concrete example: 5,000 dollars at 24 percent APR costs about 100 dollars a month in interest alone. Every extra 200-dollar payment is 200 dollars of future interest destroyed. Stop using the cards while you pay them down, or you are bailing water with a hole in the bucket.
Automate the Boring Parts
Willpower is unreliable; automation is not. Set up three automatic moves and your money goals run themselves. One: pay yourself first with an automatic transfer to savings on payday, before you can spend it. Two: automate bill payments to kill late fees forever. Three: if your employer offers a retirement match, contribute enough to capture the full match; it is an instant 100 percent return. Review the automation quarterly, not daily. The less you touch the system, the better it works.
Small 2027 Money Wins That Add Up
Big goals are built from small wins. Pick three of these for January:
- The 24-hour rule: Wait a full day before any non-essential purchase over 50 dollars. Most urges die overnight.
- No-spend weekends: Two weekends a month with zero discretionary spending. Cook, hike, borrow entertainment.
- Negotiate one bill: Call your internet, phone, or insurance provider and ask for a better rate. A 20-minute call often saves 200 dollars a year.
- Cancel and consolidate: Kill duplicate subscriptions and downgrade the ones you barely use.
- One extra income stream: Freelance, sell unused items, or pick up occasional gig work, and direct 100 percent of it to your goal.
- The 50/30/20 check: Aim for roughly 50 percent of income to needs, 30 percent to wants, 20 percent to savings and debt. Adjust the ratios to your reality.
Write your top three money goals on paper and put them where you will see them: the fridge, the bathroom mirror, the phone lock screen. Then automate the first step this week. By December 2027, the person who set up the automatic transfer in January will be unrecognizably better off than the person who just resolved to "save more."